ARM Holdings Plc Reports Results For The Third Quarter And Nine Months Ended 30 September 2012
A conference call discussing these results will be audiocast today at 09:30 BST at www.arm.com/ir
CAMBRIDGE, UK, 23 October 2012 — ARM Holdings plc announces its unaudited financial results for the third quarter and nine months ended 30 September 2012.
| Q3 2012 – Financial Summary |
Normalised* |
|
IFRS |
|||||||||
|
Q3 2012 |
Q3 2011 |
% Change |
|
Q3 2012 |
Q3 2011 |
|||||||
| Revenue ($m) |
227.9 |
192.3 |
18% |
|
227.9 |
192.3 |
||||||
| Revenue (£m) |
144.6 |
120.2 |
20% |
|
144.6 |
120.2 |
||||||
| Operating margin |
44.6% |
44.6% |
|
|
35.8% |
34.0% |
||||||
| Profit before tax (£m) |
68.1 |
55.7 |
22% |
|
55.3 |
43.0 |
||||||
| Earnings per share (pence) |
3.71 |
3.05 |
22% |
|
2.96 |
2.29 |
||||||
| Net cash generation** |
88.0 |
43.7 |
|
|
|
|
||||||
| Effective revenue fx rate ($/£) |
1.58 |
1.60 |
|
|
|
|
||||||
| YTD 2012 – Financial Summary |
Normalised* |
|
IFRS |
|||||||||
|
YTD 2012 |
YTD 2011 |
% Change |
|
YTD 2012 |
YTD 2011 |
|||||||
| Revenue ($m) |
650.3 |
568.0 |
14% |
|
650.3 |
568.0 |
||||||
| Revenue (£m) |
412.7 |
354.0 |
17% |
|
412.7 |
354.0 |
||||||
| Operating margin |
45.2% |
43.9% |
|
|
36.7% |
28.8% |
||||||
| Profit before tax (£m) |
196.6 |
160.7 |
22% |
|
161.6 |
107.3 |
||||||
| Earnings per share (pence) |
10.63 |
8.75 |
22% |
|
8.48 |
5.79 |
||||||
| Net cash generation** |
193.3 |
152.3 |
|
|
|
|
||||||
| Effective revenue fx rate ($/£) |
1.58 |
1.60 |
|
|
|
|
||||||
Progress on key growth drivers in Q3
- Growth in adoption of ARM® processor technology
- 29 processor licenses signed for a broad range of applications, including deeply embedded products such as chips for hearing aids and automotive braking systems, and consumer electronics such as smartphones, TVs and tablets
- Momentum in high-end computing and networking applications continued, with the signing of one ARMv8 architecture license, one ARMv8 processor license and one Cortex-A15 processor license
- Growth in shipments of chips based on ARM processor technology
- 2.2 billion chips shipped, split equally between mobile and non-mobile segments
- Processor royalty revenue grew 27% year-on-year, driven by strong growth in Cortex-A and Mali-based chip
- Growth in outsourcing of new technology
- Mali™ graphics processor licenses signed, including three with new customers for Mali technology
- 4 physical IP Processor Optimisation Packs licensed, enhancing ARM’s royalty opportunity per chip
Warren East, Chief Executive Officer, said:
“ARM has delivered another quarter of strong revenue and earnings growth. As we move into an ever more connected world of mobile computing, cloud-based networks and the Internet-of-Things, ARM is seeing increased demand for its high performance and low power technology. This demand is helping to drive ARM’s licensing revenues and this quarter we saw market leaders license ARM’s advanced processor technology for next generation super smartphones, tablets, and mobile and embedded computing applications.
ARM’s royalty revenues outpaced the industry with continued market share gains in key end markets including digital TVs and microcontrollers. The increasing penetration of Cortex-A class technology and adoption of Mali graphics in consumer electronics also helped increase ARM’s overall royalty revenue per chip. This strong growth in licensing and royalty revenue allows ARM to keep investing for the future and deliver increased profits and cash generation.”
Outlook
ARM enters the final quarter of 2012 with record order backlog and a robust opportunity pipeline. This combination points to another strong quarter for licensing revenue in Q4. ARM’s Q4 royalty revenue is generated from third quarter chip shipments. Data from our customers suggests a moderate sequential increase in ARM’s royalty revenue in Q4
| Q3 2012 – Revenue Analysis |
Revenue ($m)*** |
|
Revenue (£m) |
||||
|
Q3 2012 |
Q3 2011 |
% Change |
|
Q3 2012 |
Q3 2011 |
% Change |
|
| PD |
|
|
|
|
|
|
|
|
Licensing |
69.7 |
59.7 |
17% |
|
44.3 |
37.8 |
17% |
|
Royalties |
106.8 |
84.2 |
27% |
|
67.8 |
52.1 |
30% |
| Total PD |
176.5 |
143.9 |
23% |
|
112.1 |
89.9 |
25% |
| PIPD |
|
|
|
|
|
|
|
|
Licensing |
13.7 |
12.9 |
6% |
|
8.6 |
8.2 |
5% |
|
Royalties1 |
14.3 |
12.6 |
13% |
|
9.1 |
7.8 |
17% |
| Total PIPD |
28.0 |
25.5 |
9% |
|
17.7 |
16.0 |
11% |
| Development Systems |
12.1 |
12.5 |
-3% |
|
7.6 |
7.8 |
-2% |
| Services |
11.3 |
10.4 |
9% |
|
7.2 |
6.5 |
11% |
|
Total Revenue |
227.9 |
192.3 |
18% |
|
144.6 |
120.2 |
20% |
| YTD 2012 – Revenue Analysis |
Revenue ($m)*** |
|
Revenue (£m) |
||||
|
YTD 2012 |
YTD 2011 |
% Change |
|
YTD 2012 |
YTD 2011 |
% Change |
|
| PD |
|
|
|
|
|
|
|
|
Licensing |
201.9 |
169.0 |
19% |
|
128.0 |
106.4 |
20% |
|
Royalties |
295.9 |
256.5 |
15% |
|
188.2 |
158.5 |
19% |
| Total PD |
497.8 |
425.5 |
17% |
|
316.2 |
264.9 |
19% |
| PIPD |
|
|
|
|
|
|
|
|
Licensing |
36.8 |
37.8 |
-3% |
|
23.3 |
23.9 |
-3% |
|
Royalties1 |
41.2 |
34.4 |
20% |
|
26.0 |
21.1 |
23% |
| Total PIPD |
78.0 |
72.2 |
8% |
|
49.3 |
45.0 |
10% |
| Development Systems |
41.0 |
39.8 |
3% |
|
26.0 |
24.8 |
5% |
| Services |
33.5 |
30.5 |
10% |
|
21.2 |
19.3 |
10% |
|
Total Revenue |
650.3 |
568.0 |
14% |
|
412.7 |
354.0 |
17% |
Includes catch-up PIPD royalties of $4.0m (£2.5m) in YTD 2012 and $2.3m (£1.4m) in YTD 2011.
* Normalised figures are based on IFRS, adjusted for acquisition-related charges, share-based payment costs, profit or loss on disposal and impairment of available-for-sale investments and Linaro™-related charges. For reconciliation of IFRS measures to normalised non-IFRS measures detailed in this document, see notes 5.13 to 5.16.
** Net cash generation is defined as movement on cash, cash equivalents, short-term and long-term deposits and borrowings, adding back dividend payments, investment and acquisition consideration, restructuring payments, other acquisition-related payments, share-based payroll taxes and Linaro-related payments, and deducting inflows from share option exercises and investment disposal proceeds – see notes 5.8 to 5.12.
*** Dollar revenues are based on the group’s actual dollar invoicing, where applicable, and using the rate of exchange applicable on the date of the transaction for invoicing in currencies other than dollars. Over 95% of invoicing is in dollars.
CONTACTS:
Sarah West/Aideen Lee
Brunswick
+44 (0)207 404 5959
Ian Thornton/Jonathan Lawton
ARM Holdings plc
+44 (0)1628 427800
Financial review (IFRS unless otherwise stated)
Total revenues
Total dollar revenues in Q3 2012 were $227.9 million, up 18% versus Q3 2011. Q3 sterling revenues of £144.6 million were up 20% year-on-year.
Year-to-date dollar revenues amounted to $650.3 million, up 14% on 2011.
License revenues
Total dollar license revenues in Q3 2012 increased by 15% year-on-year to $83.4 million, representing 37% of group revenues. License revenues comprised $69.7 million from PD and $13.7 million from PIPD.
Group order backlog at the end of Q3 2012 was up 6% sequentially and is now at its highest ever level. Prospects for order backlog in Q4 2012 look promising, given the strength of the licensing opportunity pipeline.
Royalty revenues
Royalties are recognised one quarter in arrears with royalties in Q3 2012 generated from semiconductor unit shipments in Q2 2012. Total dollar royalty revenues in Q3 2012 increased year-on-year by 25% to $121.1 million, representing 53% of group revenues. This compares with industry revenues1 increasing by about 4% in the shipment period (i.e. Q2 2012 compared to Q2 2011), demonstrating ARM’s continuing market share gains over the last 12 months.
Royalty revenues comprised $106.8 million from PD and $14.3 million from PIPD.
Development Systems and Service revenues
Sales of development systems in Q3 2012 were $12.1 million, a decrease of 3% year-on-year and representing 5% of group revenues. Through 2012 ARM is continuing to transition the Development Systems business to focus on microcontroller tools and premium toolkits for multi-core systems. The transition remains on track and we expect Development Systems to achieve its stated target of being broadly flat year-on-year.
Service revenues in Q3 2012 were $11.3 million, an increase of 9% year-on-year and representing 5% of group revenues.
Gross margins
Gross margins in Q3 2012, excluding the share-based payments charge of £0.5 million (see below), were 94.6% compared to 95.1% in Q2 2012 and 94.9% in Q3 2011.
Operating expenses and operating margin
Normalised income statements for Q3 and YTD 2012 and Q3 and YTD 2011 are included in notes 5.13 to 5.16 below which reconcile IFRS to the normalised non-IFRS measures referred to in this earnings release.
Normalised operating expenses (excluding acquisition-related, share-based payment and restructuring charges) were £72.3 million in Q3 2012 compared to £66.0 million in Q2 2012 and £60.5 million in Q3 2011. Operating expenses in Q3 2012 were impacted by a net charge of approximately £2 million due to the impact of a weaker dollar on the accounting of derivative instruments (compared to a net credit of approximately £2 million in Q2 2012). The underlying year-on-year increase in operating expenses in the third quarter is primarily due to the increased investment in our research and development teams over the last 12 months.
Normalised operating expenses in Q4 2012 (assuming effective exchange rates similar to current levels) are expected to be in the range £71-73 million.
Normalised operating margin was 44.6% in Q3 2012, compared to 46.4% in Q2 2012 and 44.6% in Q3 2011.
Normalised research and development expenses were £32.2 million in Q3 2012, representing 22% of revenues, compared to £32.8 million in Q2 2012 and £29.8 million in Q3 2011. Normalised sales and marketing expenses were £15.6 million in Q3 2012, being 11% of revenues, compared to £15.0 million in Q2 2012 and £15.5 million in Q3 2011. Normalised general and administrative expenses were £24.5 million in Q3 2012, representing 17% of revenues, compared to £18.2 million in Q2 2012 and £15.2 million in Q3 2011.
Total IFRS operating expenses in Q3 2012 were £84.6 million (Q3 2011: £72.4 million) including share-based payment costs and related payroll taxes of £10.6 million (Q3 2011: £10.9 million), and amortisation of intangible assets and other acquisition-related charges of £1.7 million (Q3 2011: £1.0 million).
Total share-based payment costs and related payroll tax charges of £11.1 million in Q3 2012 were included within cost of revenues (£0.5 million), research and development (£6.1 million), sales and marketing (£1.8 million) and general and administrative (£2.7 million).
Earnings and taxation
Profit before tax was £55.3 million in Q3 2012 compared to £43.0 million in Q3 2011. After adjusting for acquisition-related and share-based payment costs, and disposal and impairment of investments, normalised profit before tax in Q3 2012 was £68.1 million compared to £55.7 million in Q3 2011. The Group’s effective normalised tax rate was 23.9% in Q3 2012 (IFRS: 25.3%) compared to 24.8% (IFRS: 27.0%) in Q3 2011. The Group’s effective normalised tax rate for the full year 2012 is estimated to be approximately 25%.
In Q3 2012, fully diluted earnings per share were 2.96 pence (14.35 cents per ADS2 ) compared to earnings per share of 2.29 pence (10.68 cents per ADS) in Q3 2011. Normalised fully diluted earnings per share in Q3 2012 were 3.71 pence (17.96 cents per ADS) compared to 3.05 pence (14.24 cents per ADS) in Q3 2011.
Balance sheet
Intangible assets at 30 September 2012 were £535.2 million, comprising goodwill of £522.6 million and other intangible assets of £12.6 million, compared to £537.6 million and £14.0 million respectively at 30 June 2012.
ARM regularly evaluates strategic opportunities and, in pursuance of one such opportunity, had conditionally committed £104.5 million as of 30 September 2012. This amount, which is classified as Other Debtors, represents the entire investment being contemplated and in the event a transaction is not completed, the amount will be returned to ARM. To avoid early termination of term deposits, £99.1 million of the amount was financed through a short term bank facility.
Total accounts receivable were £98.3 million at 30 September 2012, compared to £106.7 million at 30 June 2012.
Days sales outstanding (DSOs) were 47 at 30 September 2012 compared to 43 at 30 June 2012.
Cash flow
Normalised free cash flow in Q3 2012 was £88.0 million. Net cash at 30 September 2012 was £477.9 million compared to £495.9 million at 30 June 2012.
Operating review
Processor licensing
A total of 29 processor licenses were signed in Q3 2012.
Seven of the licenses signed were for ARM’s Cortex™-A series processors. This included a further licensee for ARM’s big.LITTLE technology, taking the total number of companies with access to the technology to 14. ARM’s Cortex-A class technology is increasingly being used beyond mobile and mobile computing applications, and this quarter we saw Cortex-A licenses for gaming, digital TVs, home entertainment systems, servers and GPS navigation systems.
Two licenses were signed with major semiconductor companies for enterprise networking applications. This included one ARMv8 architecture license and one v8 processor license. ARM is seeing increasing demand for the use of its technology in high-end networking applications. The rapid growth in mobile computing devices and the subsequent increase in data traffic is placing unprecedented demand on networking infrastructure. As the cost increases to maintain this infrastructure so the network operators are looking at ways to reduce their energy consumption. ARM’s scalable high performance, low power technology is ideally suited to these applications.
Demand for ARM’s range of processors for the embedded market remained strong with a further 13 licenses for its Cortex-M class technology being signed in Q3, taking the total number of licenses signed to over 160. These processors were licensed for a broad range of end applications from automotive braking systems to storage and industrial control systems.
ARM also signed 5 licenses for its Mali graphics processors. Three of the five licenses were with companies taking their first Mali license from ARM.
|
Existing |
New |
Quarter |
Cumulative Total* |
|
| ARM7™ |
|
|
|
171 |
| ARM9™ |
|
2 |
2 |
273 |
| ARM11™ |
|
|
|
79 |
| Cortex-A |
4 |
3 |
7 |
117 |
| Cortex-R |
1 |
|
1 |
28 |
| Cortex-M |
8 |
5 |
13 |
162 |
| Mali |
5** |
|
5 |
68 |
| Other |
1 |
|
1 |
22 |
| Total |
19 |
10 |
29 |
920 |
* Adjusted for licenses that are no longer expected to generate royalties
** Includes three existing ARM customers taking their first Mali license
Processor Design Wins and Ecosystem Development
Many leading technology companies have announced details of their ARM-based product developments in recent months. These included:
- Microsoft providing more details on upcoming WindowsRT devices, with confirmed product announcements from Asus, Dell, Lenovo, Samsung and Microsoft;
- Fujitsu, MediaTek, Nufront, Rockchip and Samsung all announcing their commitment to the latest range of graphics processors (GPU) available from ARM. The Mali-T600 range of products is aimed at super-smartphone and mobile computing applications and can support general purpose (GP) computing. So called GP GPU computing improves energy efficiency and enables applications such as computational photography, multi-perspective views and real-time photo editing on mobile devices;
- Several ARM partners announcing new elements of their microcontroller (MCU) strategies:
- Atmel released a new family of Cortex-M4-based MCUs for ultra low power applications;
- Freescale announced range of ARM-based Cortex-M0+ MCUs designed to help migrate consumer and industrial applications currently using legacy 8- and 16-bit architectures to ARM MCUs;
- Silicon Labs announced a new family of ultra low power Cortex-M3 products aimed at smart metering, medical devices and other power-sensitive Internet-of-Things applications.
Many more partner announcements can be found on the ARM website at www.arm.com/news.
Processor royalties
Royalties are recognised one quarter in arrears with royalties in Q3 generated from semiconductor unit shipments in Q2. PD dollar royalty revenues in Q3 2012 increased 27% year-on-year. This compares with industry revenues increasing by about 4%3 in the relevant shipment period (i.e. Q2 2012 compared to Q2 2011). Q3 revenue came from the sales of about 2.2 billion ARM-based chips, up 16% year-on-year.
ARM’s average royalty revenue per chip increased to 4.9 cents, compared to 4.4 cents one year ago, driven primarily by the growth in Cortex-A class processor shipments (more than doubling year-on-year) and in the number of chips containing Mali graphics (more than fourfold year-on-year). ARM typically receives a higher royalty percentage for chips incorporating Cortex-A class processors and an additional royalty if these chips also contain a Mali graphics processor.
Cortex-A class processors now account for 9% of ARM’s total processor shipments, up from 5% one year ago. As well as carrying a higher royalty percentage, Cortex-A class processors are usually found in higher value chips. As a result, Cortex-A class chips comprise 9% of unit shipments and 35% of royalty value.
ARM’s mobile shipments were up 6% year-on-year and grew faster than the handset market, which was down slightly over the same period. ARM also continued to gain share in non-mobile end-markets. Non-mobile processor shipments now represent 50% of all ARM-based shipments. Shipments of ARM technology-based digital TVs and set-top-boxes were particularly strong, more than doubling year-on-year, compared to a flat market. ARM-based microcontrollers also continue to ship strongly, increasing 35% year-on-year, compared to less than 20% growth for the overall microcontroller market.
| Processor Family |
Unit Shipments |
Market |
Unit Shipments |
|
| ARM7 |
37% |
Mobile |
50% |
|
| ARM9 |
20% |
Enterprise |
18% |
|
| ARM11 |
9% |
Home |
5% |
|
| Cortex-A |
9% |
Embedded |
27% |
|
| Cortex-R |
3% |
|||
| Cortex-M |
22% |
|||
PIPD licensing
During the quarter ARM signed a multi-year agreement with GLOBALFOUNDRIES to jointly deliver optimised ARM-based system-on-chip designs on both GLOBALFOUNDRIES’ 20nm process and 14nm FinFET process. These royalty bearing platforms will enable ARM’s partners to realise state-of-the-art ARM-based processors with improved performance and power efficiency for next generation mobile and mobile computing applications. ARM also signed a platform license with a leading foundry at 110nm bringing the total number of platform licenses signed to date to 96.
|
Process Node |
Total |
|
Platform analysis |
Royalty Bearing Foundry |
|
|
(nm) |
|
|
(nm) |
Platforms at Each Node * |
|
| New Royalty Bearing Foundry Platform Licenses |
14nm
|
1 |
|
16/14 22/20 |
2 4 |
|
|
32/28 |
8 |
|||
|
45/40 |
6 |
||||
|
|
|
|
65 |
11 |
|
|
Total for Quarter |
Cumulative Total |
|
90 |
8 |
|
|
|
130 |
20 |
|||
| Processor Optimisation Packs |
4 |
36 |
|
180 to 250 |
37 |
|
|
Total |
96 |
ARM continues to see strong demand for physical IP optimised for use with processors (POPs). POPs enable the licensee to more readily achieve a high-performance, low-power processor implementation through specially optimised physical IP technology. For every chip implemented using a POP, ARM receives a royalty both for the processor in the chip and for the physical IP. During the quarter ARM signed four licenses for POPs bringing the total number of POPs licensed to 36.
PIPD royalties
Royalties are recognised one quarter in arrears with royalties in Q3 generated from semiconductor unit shipments in Q2. Underlying PIPD royalties in Q3 2012 were $13.9 million, up 28% year-on-year.
People
At 30 September 2012, ARM had 2,368 full-time employees, a net increase of 252 since the start of the year, being mainly engineers joining ARM’s processor R&D teams. At the end of Q3, the group had 977 employees based in the UK, 580 in the US, 296 in Continental Europe, 344 in India and 171 in the Asia Pacific region.
Principal risks and uncertainties
The principal risks and opportunities faced by the Group are included within the “Risks and risk management” section of the 2011 Annual Report and Accounts filed with Companies House in the UK. Details of other risks and uncertainties faced by the Group are noted within the Annual Report on Form 20-F for the year ended 31 December 2011 which is on file with the Securities and Exchange Commission (the “SEC”) and is available on the SEC’s website at www.sec.gov. There have been no changes to these risks that would materially impact the group in the foreseeable future. These include but are not limited to: ARM’s quarterly results may fluctuate significantly and be unpredictable which could adversely affect the market price of ARM ordinary shares; general economic conditions may reduce ARM’s revenues and harm its business; ARM may have to protect its intellectual property or defend ARM’s technology against claims that we have infringed others’ proprietary rights; an infringement claim against ARM’s technology may result in a significant damages award which would adversely impact ARM’s operating results; companies within the semiconductor industry may consolidate reducing the number of customers that ARM may sell its technology to; for ARM to enter new markets or develop new technology may require significant investment and may not result in profitable operations; and ARM competes in the intensely competitive semiconductor market.
Notes
The results shown for Q3 2012, Q2 2012, Q3 2011, 9M 2012, and 9M 2011 are unaudited. The results shown for FY 2011 are audited. The consolidated financial information contained in this announcement does not constitute statutory accounts within the meaning of Section 434 of the Companies Act 2006. Statutory accounts of the Company in respect of the financial year ended 31 December 2011 were approved by the Board of directors on 27 February 2012 and delivered to the Registrar of Companies. The report of the auditors on those accounts was unqualified and did not contain an emphasis of matter paragraph nor any statement under Section 498 of the Companies Act 2006.
The results for ARM for Q3 2012 and previous quarters as shown reflect the accounting policies as stated in Note 1 to the financial statements in the Annual Report and Accounts filed with Companies House in the UK for the fiscal year ended 31 December 2011 and in the Annual Report on Form 20-F for the fiscal year ended 31 December 2011.
This document contains forward-looking statements as defined in section 102 of the Private Securities Litigation Reform Act of 1995. These statements are subject to risk factors associated with the semiconductor and intellectual property businesses. When used in this document, the words “anticipates”, “may”, “can”, “believes”, “expects”, “projects”, “intends”, “likely”, similar expressions and any other statements that are not historical facts, in each case as they relate to ARM, its management or its businesses and financial performance and condition are intended to identify those assertions as forward-looking statements. It is believed that the expectations reflected in these statements are reasonable, but they may be affected by a number of variables, many of which are beyond our control. These variables could cause actual results or trends to differ materially and include, but are not limited to: failure to realize the benefits of acquisitions, unforeseen liabilities arising from acquisitions, price fluctuations, actual demand, the availability of software and operating systems compatible with our intellectual property, the continued demand for products including ARM’s intellectual property, delays in the design process or delays in a customer’s project that uses ARM’s technology, the success of our semiconductor partners, loss of market and industry competition, exchange and currency fluctuations, any future strategic investments or acquisitions, rapid technological change, regulatory developments, ARM’s ability to negotiate, structure, monitor and enforce agreements for the determination and payment of royalties, actual or potential litigation, changes in tax laws, interest rates and access to capital markets, political, economic and financial market conditions in various countries and regions and capital expenditure requirements. More information about potential factors that could affect ARM’s business and financial results is included in ARM’s Annual Report on Form 20-F for the fiscal year ended 31 December 2011 including (without limitation) under the captions, “Risk Factors”(on pages 4 to 11) which is on file with the Securities and Exchange Commission (the “SEC”) and available at the SEC’s website at www.sec.gov. About ARM ARM designs the technology that lies at the heart of advanced digital products, from wireless, networking and consumer entertainment solutions to imaging, automotive, security and storage devices. ARM’s comprehensive product offering includes 32-bit RISC microprocessors, graphics processors, video engines, enabling software, cell libraries, embedded memories, high-speed connectivity products, peripherals and development tools. Combined with comprehensive design services, training, support and maintenance, and the company’s broad Partner community, they provide a total system solution that offers a fast, reliable path to market for leading electronics companies. More information on ARM is available at http://www.arm.com. ARM is a registered trademark of ARM Limited. ARM7, ARM9, ARM11, Cortex and Mali are trademarks of ARM Limited. All other brands or product names are the property of their respective holders. “ARM” is used to represent ARM Holdings plc; its operating company ARM Limited; and the regional subsidiaries: ARM Inc.; ARM KK; ARM Korea Ltd.; ARM Taiwan Limited; ARM France SAS; ARM Consulting (Shanghai) Co. Ltd.; ARM Belgium Services BVBA; ARM Germany GmbH; ARM Embedded Technologies Pvt. Ltd.; ARM Norway AS; and ARM Sweden AB.
Any re-use permitted for informational and non-commercial or personal use only.


Latest on X

Build. Test. Experiment.
You won't want to miss the Arm Create Builder Zone at @WeAreDevs World Congress North America.
⬇️⬇️⬇️
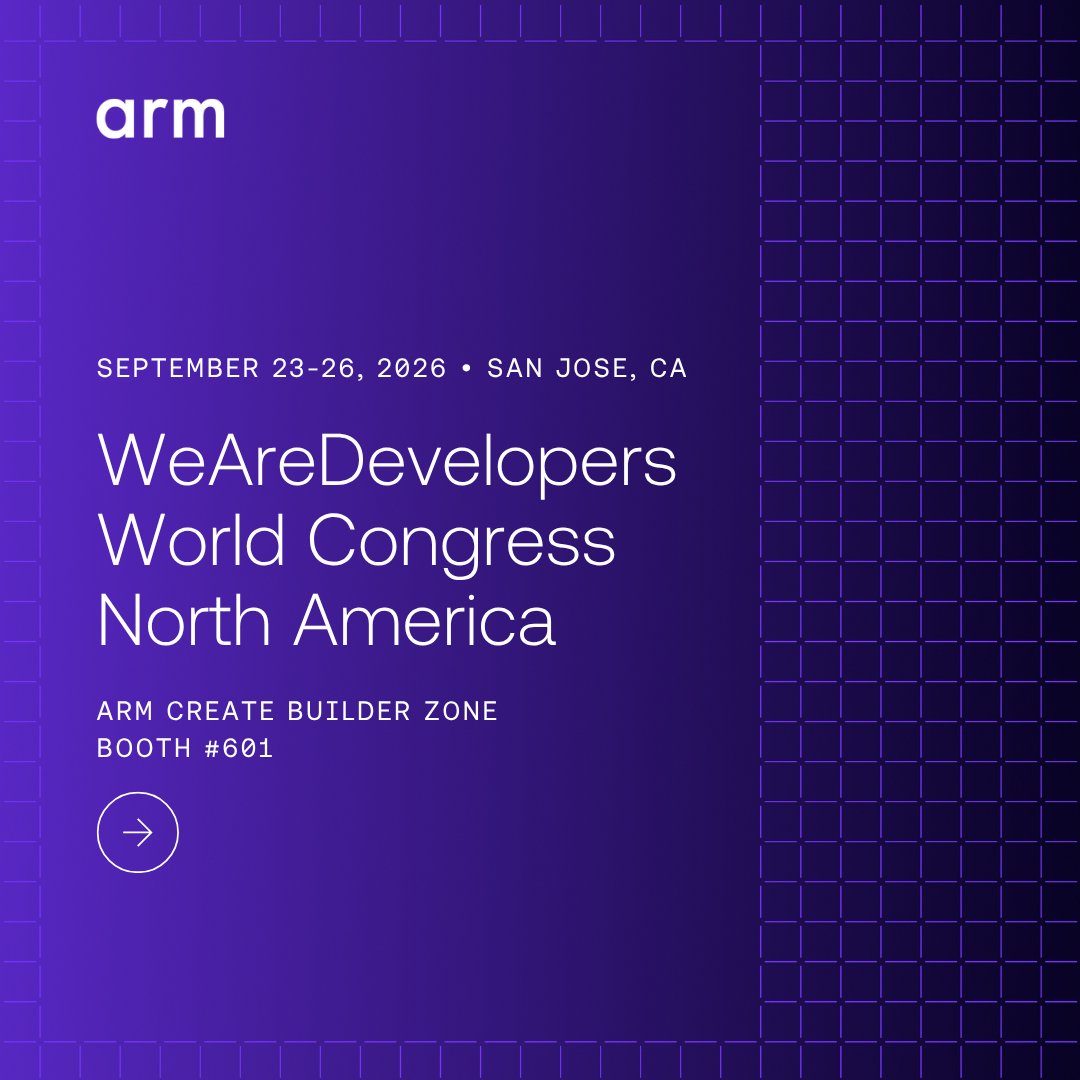
The Arm Create Builder Zone coming to @WeAreDevs World Congress North America!
🚀 Lightning talks
🚀 Demos
🚀 Conversations with the teams building the next era of AI
This is your chance to learn more about how YOU can build, test, and experiment on Arm.
Come and see us
What could AI make possible that we can’t imagine today?
Arm CEO Rene Haas talks to @BBC’s @faisalislam about the potential for AI to transform healthcare, including breakthroughs in diseases like cancer. https://okt.to/qHwKnr

Today’s @Snap SPECS launch offers an exciting look at that future—where immersive experiences can help people create, connect, and get things done while staying present in the moment.
As intelligence increasingly moves to the edge, experiences like these show what’s possible

SPECS bring useful digital experiences into the world around you while keeping you present in the moment. From work and navigation to entertainment, creativity, and connection.
https://SPECS.com
Congrats to @MediaTek on the Dimensity 9600 Pro. 🎉
Featuring the Arm C2 CPU cluster with C2-Ultra CPUs and the Mali G2-Ultra NX GPU, the new flagship SoC delivers high performance and power efficiency for faster, more responsive mobile experiences.

MediaTek Dimensity 9600 Pro Sets New Standard for Flagship Smartphone Chips
MediaTek Dimensity 9600 Pro Sets New Standard for Flagship Smartphone Chips. This 2nm SoC delivers leap in performance and efficiency for agentic AI.
okt.to
What makes Arm CSS for Mobile 2 more than a collection of IP? 📱
It brings together world-class AI CPU and GPU capabilities, including the Arm C2 CPU Cluster with SME2 and Mali G2-Ultra NX, with system technologies and software in one configurable AI-native platform.
@ctbergey

Our latest Sustainable Business Report is now live - take a closer look to see how we’re advancing power-efficient computing and working with partners to expand access to technology, skills, and opportunity.
Flip through our FYE26 highlights 👇 then explore the full report 👉



Thank you to the @verdacloud team for joining us at Arm in San Jose as we continue to build the foundation for scalable, production-ready AI systems. 💪
Verda’s adoption of the Arm AGI CPU reflects a broader trend toward integrated, heterogeneous systems optimized for AI, where